Steve Miller's Blog

A digital workshop for systems-minded tech commentary.

Author: steve

  • AI Data Centers Aren’t Cooking the Planet Alone—But the Polls and the Megawatts Are Getting Awkward

    AI Data Centers Aren’t Cooking the Planet Alone—But the Polls and the Megawatts Are Getting Awkward

    I’ve spent too many years staring at power bills, cooling loops, and capacity tickets to pretend every AI prompt is personally boiling the oceans. That kind of slogan is great for clicks and terrible for capacity planning. The real story is less theatrical and more operational: data-center load is growing fast enough that utilities, grids, and neighbors are noticingand the public opinion numbers are catching up to the megawatt math.

    The old stub on this URL invented a cute “poll with neat percentages and a punchline about ChatGPT as your intern. I’m not recycling invented survey numbers. We have a real one.

    What Americans Actually Told Pew

    In January 2026, Pew Research Center surveyed 8,512 U.S. adults about data centers—buildings full of the gear that runs streaming, banking, cloud apps, and, yes, AI. Among people who had heard of them, the mood on the environment was not warm:

    • 39% said data centers are mostly bad for the environment; only 4% said mostly good.
    • 38% said they are mostly bad for home energy costs; 6% said mostly good.
    • 30% said they hurt nearby quality of life; 6% said the opposite.
    • Views flipped more positive on local jobs (25% mostly good vs. 15% mostly bad) and tax revenue (23% vs. 12%).

    That is the poll nobody in a ribbon-cutting hard hat wants on a slide deck. The public will tolerate a warehouse full of servers if it brings payroll and property tax. They get less charitable when the same facility shows up in their summer power bill narrative—or when local media covers water for cooling next to a drought map.

    The operational takeaway is simple: awareness is up, and the default story is load that someone else is paying for.”

    Read the survey yourself: Pew — How Americans view data centers’ impact.

    What the IEA Says the Load Actually Looks Like

    Opinion is downstream of physics. The International Energy Agency’s Energy and AI report put hard numbers under the hype:

    • Data centers used about 415 TWh in 2024—roughly 1.5% of global electricity.
    • In the IEA Base Case, that roughly doubles to ~945 TWh by 2030, still under 3% of global electricity but growing ~15% a yearseveral times faster than everything else.
    • A typical AI-focused site can draw as much power as ~100,000 households; the largest campuses under construction are described as roughly 20x that.
    • Emissions from data-center electricity use rise from about 180 Mt today toward ~300 Mt by 2035 in the Base Case (higher in a Lift-Off case)still a small slice of energy-sector emissions, but one of the fastest-growing slices.
    • In the United States, data centers account for nearly half of projected electricity demand growth to 2030 in IEA’s framing—enough that by decade’s end the country could use more power for data centers than for aluminum, steel, cement, chemicals, and other energy-intensive goods combined.

    IEA also notes the uncomfortable local truth: globally the share looks manageable; in a handful of U.S. clusters it does not. Nearly half of U.S. data-center capacity sits in five regional clusters. Grid queues are long. Transformers and cables have multi-year lead times. The agency estimates that without mitigation, around 20% of planned projects could face delay risk.

    Primary source: IEA Energy and AI, executive summary.

    U.S. Power Demand Is Not Flat Anymore

    You do not need a white paper to feel this if you watch Short-Term Energy Outlook headlines. The U.S. Energy Information Administration has been forecasting record electricity use into 2026-2027, with data-center development (plus manufacturing and electrification) as a named driver. Commercial load—where standalone data centers live in the accounting—is no longer a sleepy line item.

    EIA’s longer Annual Energy Outlook work also flags server electricity as a rising share of commercial consumption. Flat end-use load shapes (servers that draw hard around the clock) are exactly the kind of customer that makes a utility’s planning spreadsheet sweat: you cannot “wait for the evening peak” if the evening peak never leaves.

    For a plain-English EIA note on server energy in the commercial stock, see EIA Today in Energy on data center server electricity. For the short-term demand narrative, Reuters summarized EIA’s STEO framing that AI-driven data centers are helping push U.S. power use to new highs: Reuters on EIA power-demand outlook.

    Water, Cooling, and the Part of the Ticket Most Dashboards Hide

    Electricity gets the press. Water is the quieter constraint. Cooling towers turn megawatts into gallons. Analyses such as Brookings look at AI energy demand cite U.S. data-center water use on the order of ~17 billion gallons in 2023, mostly at hyperscale and colocation sites. Disclosures still vary by methodology—if you do not measure WUE the same way, you cannot compare vendors in a bake-off.

    I used to review “green” claims like backup-generator test logs: politely, then with a red pen. Annual renewable certificates are not the same as sparing a local summer peak. Carbon-aware scheduling, workload shifting, and honest siting are the grown-up conversation.

    Policy Is Catching Up to the Cable Tray

    Regulators already treat interconnection like a scarce resource. Pause-and-study cycles happen when the load queue outruns generation and transmission—capacity management with a political overlay, not anti-tech theater.

    For IT and cloud buyers, the homework is overdue:

    1. Ask for location and carbon intensity of inference, not just training PR. Training is the fireworks; inference is the always-on baseline.
    2. Prefer vendors who publish PUE, WUE, and hourly renewable matching—or admit they do not.
    3. Right-size models. A 70B-parameter model for rewriting a meeting invite is the energy equivalent of spinning up a mainframe to balance a checkbook.
    4. Track Scope 2 like an SLA. If your board cares about emissions, treat provider region choice like latency: measure it.

    The Honest Middle

    IEA is careful here, and so am I. Data-center emissions are not “cooking the planet by themselves relative to the whole energy system. Pretending AI will single-handedly solve climate change is equally silly. Existing AI applications could unlock material efficiency gains in industry, grids, and buildings if data, incentives, and cybersecurity allow adoption. Rebound effects are real. Silver bullets are marketing.

    From Mason, Ohio, my driveway does not host a hyperscale campus. My power bill still lives in a regional market shaped by whoever is adding firm load next door. The Pew numbers say neighbors notice. The IEA numbers say the load is real. The useful response is not guilt about every prompt. It is treating compute like the industrial process it has become: site it where the grid can feed it, cool it without draining the wrong aquifer, measure it honestly, and stop confusing convenience with free energy.

    Steve Miller — Mason, Ohio. Former programmer, sysadmin, and IT manager. Still asks for the PUE before the press release.
  • How a Saudi Pipeline Outage Hits Your Gas Pump (and Your Diesel Bill)

    How a Saudi Pipeline Outage Hits Your Gas Pump (and Your Diesel Bill)

    When gasoline jumps overnight and diesel sets another ugly record, the cable-news frame is usually geopolitics. Fair enough. The ops frame is different: a damaged export path, thin terminal inventory, wider freight spreads, and a retail market that clears pain through the pump with a lag measured in days – not press conferences.

    Saudi Arabia’s East-West Pipeline (Petroline) was forced offline after attacks on pumping infrastructure around September 10-11, 2026. This piece is about how that outage transmits into U.S. pump prices and freight costs – not a rehash of the systems-failover write-up already live elsewhere on this site. Same pipe. Different ticket: retail gas, diesel, and the logistics chain that fills both.

    What Went Offline (and Why Retail Cares)

    Petroline moves crude from eastern Saudi fields west to Red Sea terminals around Yanbu – the path that mattered more than usual while Strait of Hormuz shipping stayed constrained. Traders told Reuters the line had been rerouting roughly 4 million barrels per day – about 4% of global supply – with Yanbu stocks good for only five to seven days of exports without fresh piped crude. Repair talk ranged from partial restart while work continues to five-to-six-week full fixes.

    Kpler’s mid-September note adds the product-market detail retail drivers feel indirectly: no Yanbu crude loadings since September 11; inventories covering only a few days of normal loadings; Aramco building a bypass aimed at restoring roughly half of throughput sooner while full repairs run four to six weeks; and about 200,000 bpd of diesel from Yasref’s Yanbu output at risk – tightening an already stressed middle-distillate complex in Europe and beyond.

    Nameplate capacity on the corridor is often cited near 7 million bpd. Pre-attack westbound crude flows sat in the multi-million-bpd range. When that corridor stops, barrels do not teleport. They wait on tankers, ship-to-ship transfers, and riskier Gulf routes – each with a freight premium attached.

    The Transmission Path to Your Pump

    U.S. retail gasoline is not a live mirror of every Middle East wire story. It is a stack:

    1. Crude benchmarks jump on lost export optionality.
    2. Crack spreads (refinery margins) widen when the missing barrels are the grades refiners wanted, or when product already looks short.
    3. Diesel moves first and hardest – freight, agriculture, and delivery fleets burn it; shortages elsewhere pull U.S. distillate into export markets even when America is a net exporter on paper.
    4. Gasoline follows as crude and co-product economics reset, with retailers lagging then leaping.

    By mid-September, U.S. coverage had national regular gasoline around the mid-$4s and diesel printing record prints north of $6 a gallon in AAA/GasBuddy snapshots cited by CBS News, with analysts explicitly naming Red Sea risk and the East-West shutdown among the drivers. Separately, ABC News quoted analysts suggesting a weeks-long closure could add on the order of 25-50 cents a gallon to U.S. gasoline, with multi-month scenarios arguing for still higher retail – while other voices said markets had already priced a chunk of the shock. Treat those as scenarios, not destiny. Duration still writes the invoice.

    Freight Is the Hidden Line Item

    Kpler’s freight section is the part most driveway conversations skip. With Petroline down, more Saudi crude leans on Hormuz-facing logistics and shuttle/ship-to-ship capacity that was already tight. Middle East Gulf-to-Asia VLCC rates were described running roughly $10/bbl above safer Gulf-of-Oman-origin comparisons – risk premium baked into the delivered barrel before any refiner’s crack math starts.

    That is why diesel can scream even when a crude balance sheet still shows only a modest global deficit. The binding constraint is not always barrels in the ground.” Sometimes it is barrels in the wrong place, on the wrong ship, with the wrong insurance quote. In IT terms: your CDN still has capacity; the peering link you actually need is on fire.

    Hormuz Context Without Double-Counting

    Anadolu Agency’s export-route explainer (citing EIA flow data) is useful for the correlated-risk picture: Hormuz liquids flows had already collapsed from tens of millions of bpd toward a much thinner wartime trickle, which is exactly why Petroline-to-Yanbu had become the workaround. Suez/SUMED cannot magically replace Petroline if crude never reaches the Red Sea. Analysts quoted there put effective disruption risk in the 3-5 million bpd band depending on how much Gulf shipping still clears – again, logistics before geology.

    If you already read the companion Petroline piece on this blog about failover architecture, think of this as the consumer-facing ticket: same outage, measured in cents per gallon and freight surcharges instead of SCADA metaphors.

    What to Watch Before You Trust a Pump Forecast

    • Bypass barrels vs. press releases. “Half capacity in days” only matters when loadings resume and stay up. Watch Yanbu sailings, not slogans.
    • Distillate inventories and cracks more than the day-one Brent print. Diesel is the household inflation sneak path – delivery fees, food, everything with a truck.
    • Midwest and regional quirks. Refinery outages at home (CBS noted Midwest sensitivity after a Chicago-area interruption) can amplify an overseas shock. Correlation is not causation, but compounding is real.
    • Do not buy fake precision. Anyone promising an exact Ohio cents-per-gallon from one Saudi pumping station is selling certainty. Anyone saying a multi-week outage at a wartime bypass route is “fully priced forever” after one session is selling calm.

    Mason Driveway Bottom Line

    I do not need a futures terminal to notice when diesel delivery and school-run gasoline both creep. Petroline’s outage is a reminder that retail fuel prices are the last hop of a long systems chain: pumps, pipes, ports, tankers, refiners, and retailers. When a few percent of world supply loses its preferred export path while other chokepoints are already stressed, you feel it as volatility at the pump – sometimes quickly, sometimes after a lag that lets everyone argue on social media first.

    Fix the pumps, restore the bypass, refill Yanbu, and the retail story softens. Stretch the outage, stack another logistics failure on top, and the spreadsheet rewrites your weekly budget. That is not panic. That is how physical infrastructure bills get paid.

    Steve Miller – Mason, Ohio. Former programmer, sysadmin, and IT manager. Still allergic to single-path “redundancy that was carrying production load.

  • Saudi East-West Pipeline Shutdown Puts ~4% of World Oil at Risk

    Saudi East-West Pipeline Shutdown Puts ~4% of World Oil at Risk

    I’ve spent enough years watching single points of failure take down carefully planned systems to recognize one when it stretches across a desert.

    Saudi Arabia’s East-West Pipeline—Petroline—was shut after drone attacks damaged pumping infrastructure around September 11, 2026. That is not a metaphor. It is a physical artery that had been moving roughly four million barrels a day toward Red Sea export terminals at Yanbu, a workaround that mattered more than usual because Gulf shipping through Hormuz has been under wartime strain. Traders told Reuters the pipeline had been carrying around 4% of global supply, with Yanbu inventories good for only days of loadings without fresh piped crude. CNN Business reported Brent and WTI jumping more than 3% as markets priced the risk.

    A week later the picture is clearer but not calm. Industry sources say pumping stations—not the whole pipe—took the hard hit. Saudi operators are reported to be building a bypass aimed at restoring about half of capacity within days, while full repairs are still discussed in the multi-week range. Yanbu loadings were suspended and some Europe-bound cargoes cancelled; Riyadh also leaned on ship-to-ship workarounds off Oman. Benchmarks pulled back midweek but stayed well north of $100. Duration still beats day-one drama.

    What Petroline actually does

    Built in the early 1980s and running about 1,200 kilometers from eastern fields toward the Red Sea, the East-West line is Saudi Arabia’s main way to export without threading every barrel through the Strait of Hormuz. Al Jazeera and market notes put recent wartime westbound flows in the 4–5 million bpd range. Nameplate capacity has been cited near seven million bpd after earlier 2026 repairs. When that path stops, Riyadh’s options shrink to east-coast terminals, longer tanker routes, and whatever west-coast stocks remain—none of which behave like elastic cloud capacity you can spin up overnight.

    Kpler’s mid-September notes are useful because they are boring and specific: the binding constraint looks like pumping damage, with repair timelines in weeks rather than hours, and a base case of temporary bypass throughput well below pre-attack rates. Inventories on the west coast drain while east-coast tankage may have room to store barrels that still need safe passage and ships.

    Primary sources worth reading yourself:

    Why your gas pump notices

    Oil is a global clearing market with local stickiness. U.S. retail gasoline does not move one-for-one with every Middle East headline, but crude spikes still feed refiners, crack spreads, and diesel—the fuel that actually moves freight. When Brent is already north of $100, another lost export corridor is not abstract geopolitics. It is a logistics problem that shows up as higher diesel first, then everything diesel hauls.

    From a systems lens, Petroline is a bypass route that became a primary path under stress. That is the classic failover trap: the backup runs so hard that losing it hurts worse than losing the original path. Hormuz risk plus Red Sea risk plus a damaged cross-peninsula pipe is correlated failure, not independent redundancy.

    What operators should watch

    1. Duration, not day-one headlines. A three-day bypass and a six-week pumping rebuild are different incidents with the same first wire story. Watch whether “half capacity in days” actually ships barrels.
    2. Product, not just crude. Distillate balances already look tight in U.S. reporting tied to Middle East disruptions; diesel is where households and warehouses feel it.
    3. Cyber and physical together. Pipelines run SCADA and sensors. Physical drones do not erase the need for digital monitoring; they remind you both layers can fail.
    4. Policy theater vs. inventory math. Diversification speeches are fine. Ullage, tanker availability, and safe transit are what refill tanks.

    I’m not going to pretend a Saudi pipeline outage automatically crashes every Ohio data center. Power markets and oil markets are related cousins, not twins. What I will say is this: when a single export bypass carries a few percent of world supply, and it goes offline while other chokepoints are already stressed, you do not need a clever cloud metaphor to understand the bill. You need repair timelines, inventory counts, and the humility to admit your “redundant” path was carrying production load.

    Ohio driveway math (without fake precision)

    I live in Mason. My weekly errands do not require a briefing on Yanbu ullage. They do require noticing when diesel-powered delivery and gasoline for school runs both creep. The transmission mechanism is familiar: benchmark crude up, product cracks stressed, retailers lag then leap. Anyone promising an exact cents-per-gallon from a single Saudi pumping station is selling certainty they do not own. Anyone pretending a multi-week outage at a wartime bypass route is “priced in forever” after one session is selling calm they also do not own.

    Watch the repair narrative the way you’d watch an incident bridge: Is the constraint pipe metal, pumps, power, security perimeter, or tanker logistics downstream? Those are different tickets with different ETAs. State media reassurances and trader inventories will disagree for a while. That disagreement is the signal.

    Also separate Petroline from the Houthi Red Sea story without ignoring correlation. One is a cross-peninsula pipe. The other is a strait and coastal control problem. Together they shrink Saudi optionality. Correlated risk is how “redundant” architectures fail in data centers; energy markets are not exempt from the same math.

    What I want next

    Clarity beats vibes. Publish damage categories and conservative restart ranges when security allows. Traders will still gossip; gossip plus fog is how spikes overshoot. For consuming countries, the homework is strategic stock discipline and refinery readiness for the crude grades you will actually receive if routes flip east. For corporate risk teams, update oil shock playbooks that still assume “Hormuz only” as the single chapter.

    Steve Miller — Mason, Ohio. Former programmer, sysadmin, and IT manager. Still allergic to calling a single failover “high availability.”

  • Why the 2026 Atlantic Season Feels Stuck: A Strengthening El Niño

    Why the 2026 Atlantic Season Feels Stuck: A Strengthening El Niño

    First, the spelling: El Niño, with the tilde. The earlier stub mangled it, a small error that signals a larger one—writing about climate drivers without reading forecast notes.

    By mid-September 2026, the Atlantic hurricane season felt strangely quiet. NOAA’s outlook favored a below-normal season: 75% chance below normal, with 7–13 named storms, 2–6 hurricanes, and 0–2 major hurricanes expected. The dominant suppressor is a strengthening El Niño, which increases wind shear and shreds developing tropical systems.

    What El Niño does to the Atlantic

    El Niño is a coupled ocean-atmosphere pattern in the equatorial Pacific. When it strengthens, Atlantic vertical wind shear often rises. Shear knocks the tops off thunderstorm towers that need to organize into hurricanes. Warm Atlantic water can still be present; organization fails anyway.

    NOAA’s Climate Prediction Center described El Niño strengthening further, with high odds of a very strong event into fall and winter 2026–27. Forecast language is probabilistic.

    Sources: NOAA outlook; CPC outlook; CPC ENSO discussion; CNN report.

    Quiet does not mean safe

    Seasonal outlooks are range forecasts; individual storm tracks improve only after storms form. Coastal hospitals, utilities, and data centers should keep hurricane playbooks active through November. “Below normal” is not “closed for the season.”

    The 2026 Atlantic’s sluggish feel tracks with strengthening El Niño and NOAA’s below-normal outlook. Steve Miller — Mason, Ohio.

  • At BRICS in New Delhi, Modi Warns on Tech “Weaponisation” as Xi Pushes AI Ambitions

    At BRICS in New Delhi, Modi Warns on Tech “Weaponisation” as Xi Pushes AI Ambitions

    BRICS summits put incompatible agendas on one stage. India’s 2026 hosting produced a tech subplot: Prime Minister Narendra Modi warned against the “weaponisation” of technology and critical minerals, while Chinese President Xi Jinping pushed open-source AI.

    What the record shows

    Modi warned that weaponising technology and critical minerals could hinder progress. China’s export controls on rare earths make that concrete, as India tries to build manufacturing without becoming a captive customer.

    Xi’s package leaned into digital and industrial cooperation, including open-source AI themes that also function as geopolitics: offer tools to the Global South, set defaults, and gain influence. The New Delhi Declaration’s mineral language is the polite version of a fight over who refines materials and who can turn off the tap.

    Sources: India Today; Scroll.in.

    Operator takeaway

    India and China remain rivals in supply chains; Russia wants payment workarounds. Track semiconductors, rare-earth magnets, batteries, cables, and cloud regions. Dual-source components and treat rival-power AI as a governance decision.

    The New Delhi meeting showed shared branding versus competition over minerals and AI stacks. Steve Miller — Mason, Ohio.

  • ACA Premiums Keep Climbing After Enhanced Subsidies Expired

    ACA Premiums Keep Climbing After Enhanced Subsidies Expired

    Health-insurance renewal feels like software that auto-renews at a higher tier—except the features are deductibles and networks. The big policy shock was simpler: enhanced ACA premium tax credits expired at the end of 2025.

    The numbers

    KFF reports average enrollee premium payments rose about 58%, from $113 to $178 per month in 2026. Many people bought down to bronze plans; others above the subsidy cliff left the market. That adverse selection feeds next year’s rates.

    For 2027, insurer filings pointed to a median increase around 14–15%, after a roughly 20% median finalized jump in the prior cycle. Insurers cite subsidy expiration alongside medical inflation and drug costs.

    Sources: KFF 2026 analysis; Peterson-KFF outlook.

    Systems view

    Enhanced credits smoothed a cliff. When they expired, people above 400% of poverty lost eligibility and faced full freight. Cliffs produce drop-offs and a sicker remaining pool. Legacy claims systems and ransomware defenses matter, but they are not the master key to this shock.

    What to do

    Shop open enrollment. Model total cost—deductible, out-of-pocket maximum, formulary, and network. Recheck income projections if taking advance credits.

    Premiums rise because care is expensive and Congress let a temporary affordability patch expire. Steve Miller — Mason, Ohio.

  • How the US–Canada Tariff Fight Shows Up in Your Grocery Cart

    How the US–Canada Tariff Fight Shows Up in Your Grocery Cart

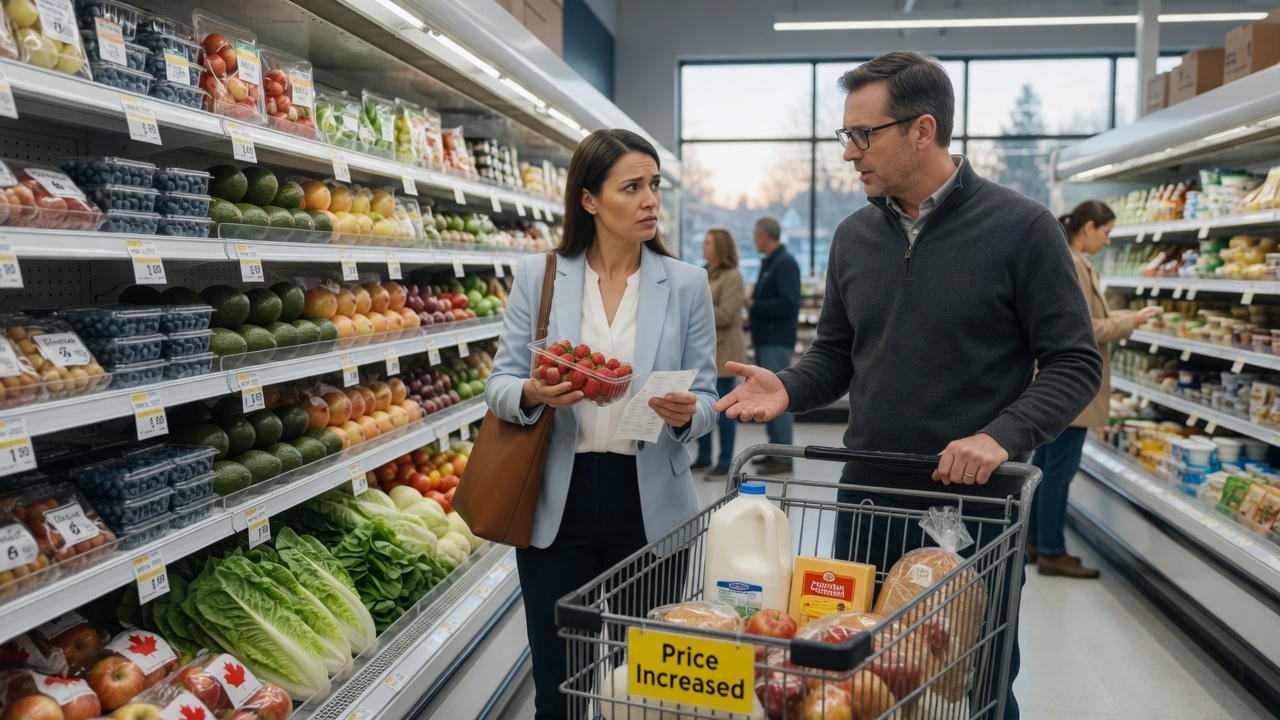
    Trade wars are abstract until the dairy case and beer aisle get weird. In late summer 2026, the United States and Canada escalated a tariff confrontation that feeds retail pricing unevenly, product by product—not as a flat “everything costs 25% more” cartoon.

    What happened

    The Trump administration imposed steep tariffs on Canadian goods including dairy, alcohol, autos-related goods, and wood/paper. Canada answered with counter-tariffs effective September 8, 2026, covering about C$27.6 billion in U.S. imports at 15%, 25%, and 50% rates. Food impacts concentrate in specific imported categories and goods using Canadian inputs.

    Sources: Canada.ca tariff list; Food Institute dairy analysis; USA Today pricing overview.

    How it reaches the receipt

    Logistics software and customs brokers ingest new duty tables, but the price signal starts with the tariff schedule. Importers pay duties; retailers decide whether to eat margin or raise shelf prices. Shoppers notice specific SKUs before national averages.

    USMCA supply chains optimized cross-border flows. Tariffs add friction: distributors hold more inventory, cash gets trapped, and smaller grocers feel stockouts first. Ohio is far from the Ambassador Bridge, but Canadian steel, lumber, paper, and packaged foods still move through Midwest channels.

    Bottom line

    Separate duties, pass-through timing, substitution, and transport effects. Read official tariff lists, not SEO metaphors. Your cart will reflect the shock selectively. Steve Miller — Mason, Ohio.

  • Missouri’s Map Fight: When Election Systems Meet Conflicting Court Orders

    Missouri’s Map Fight: When Election Systems Meet Conflicting Court Orders

    Missouri’s 2026 map fight resembles two monitoring systems disagreeing about which server is primary. Different courts issued incompatible instructions; voters had to ask which district governs November.

    The short version

    In 2025, the legislature passed HB 1, a mid-decade redraw described as aiming for a 7–1 Republican House advantage. After Secretary of State Denny Hoskins rejected referendum signatures on Aug. 4, 2026, litigation exploded.

    On Sept. 3, the Missouri Supreme Court held the referendum valid, HB 1 never took effect, and the 2022 map remains in force unless voters approve the new one. Justice Kavanaugh rejected emergency relief; a federal order to use HB 1 was stayed. Mid-September reporting said the 2022 lines govern November.

    Sources: NBC News; SCOTUSblog; Missouri Times.

    Election infrastructure

    County authorities need one district file: GIS polygons tied to voter rolls, ballot styles, and precinct programming. Conflicting orders create configuration drift. If a primary used Map A and the general might use Map B, voters experience a DNS cutover without a TTL plan.

    Publish one official bulletin channel, pre-clear GIS cutover runbooks, and train poll workers on “which map?” before early voting. Treat court orders like production configs: one source of truth and clear rollback. Steve Miller — Mason, Ohio.

  • No, Tim Cook Didn’t Buy a Galaxy Fold—Samsung Hired a Different Tim Cook

    No, Tim Cook Didn’t Buy a Galaxy Fold—Samsung Hired a Different Tim Cook

    If you skimmed a headline about Tim Cook buying a Samsung Galaxy Fold and felt your bullshit detector vibrate, good. Keep that detector.

    Samsung New Zealands Galaxy Z Fold 8 campaign did not catch Apple’s longtime CEO moonlighting at a carrier store. It cast a Palmerston North real-estate agent who is also named Tim Cook—Harcourts agent, local nickname “Palmy,” glasses and understated clothes close enough to make the joke land. The spot opens with “Tim Cook has an announcement. And for once, its about Galaxy,” then walks through Apple-style product-speak before the punchline: quote him, Tim Cook from Palmerston North. International Business Times Australia covered the ad in detail on September 12, 2026.

    Timing is the real product feature

    Samsung published the bit a day after Apple’s September 9 “Surprise and Shine event introduced the iPhone Duo—Apple’s first foldable phone—alongside the rest of the autumn lineup. Foldables still punch below their PR weight: Counterpoint Research figures cited in coverage put them around 2% of global smartphone sales. Samsung has been iterating since the original Galaxy Fold in 2019. Apple’s arrival is both threat and category expander. The ad’s job is to say, cheerfully, that Samsung already lives here.

    Theres a second timing wrinkle worth noting carefully. Coverage of that same Apple event described a leadership handoff moment on stage—Cook appearing briefly before gesturing to John Ternus as successor. Treat “former CEO” language in secondary write-ups as reporting of that transition narrative, not as an invitation to invent board minutes.

    The marketing joke works either way: a name-collision Tim Cook reviewing a Fold while Apple finally ships a foldable.

    Why a sysadmin cares about a silly ad

    Marketing stunts are usually noise. This one is a clean case study in namespace collision—the same bug that bites IT when two systems share a hostname and everyone assumes they mean the same machine. Consumers (and more than a few journalists) resolve “Tim Cook” to one famous referent. Samsung’s creative team counted on that resolution, then broke it on purpose. That is not deep strategy. It is effective DNS poisoning for attention.

    Cross-ecosystem device decisions, by contrast, are infrastructure choices. If you actually run both iOS and Android fleets—or you personally test competitor hardwareyou inherit real work: MDM profiles, backup silos, app parity gaps, and security-update calendars that refuse to sync.

    The stub’s vague warning about fragmented security updates” was directionally right and emotionally oversold. The ad itself does not create that problem. Dual-homing does.

    Rivalry theater vs. product substance

    Samsung has a long habit of needling Apple—queue jokes, notch haircuts, “Ingenious” spots about missing chargers and headphone jacks. This Tim Cook gag sits in that lineage. It also lands in a week when foldable reliability, hinge durability, software multitasking, and enterprise management matter more than cameos.

    Questions Id ask before treating any Fold vs. Duo tweetstorm as gospel:

    1. What is the warranty and repair story when the hinge fails outside a major metro?
    2. How does split-screen / multitasking behave under MDM, not just in a keynote demo?
    3. Are security patches on a predictable cadence for the exact SKU your company would buy?
    4. Can your backup and identity stack survive a user who keeps one device just for testing”?

    None of those answers come from a New Zealand realtor saying the future is here.”

    Enterprise procurement, not stan Twitter

    If you buy phones for a living, Samsung’s gag changes nothing about your RFP. Apple entering foldables may change spare-parts availability, MDM feature matrices, and user expectations—“why can’t my work phone fold?” is about to become a helpdesk ticket category. Samsung’s multiyear head start matters for repair ecosystems and accessory markets. Apple’s distribution muscle matters for making foldables feel normal to people who never wanted a Galaxy Fold brochure.

    I’m old enough to remember every “this form factor replaces the laptop” sermon. Most didn’t. Some carved niches. The sane IT posture is pilot fleets, clear support boundaries, and a written rule about whether personal competitor devices may touch corporate mail. Marketing cameos do not belong in that policy documentexcept maybe as a footnote explaining why your CFO forwarded a confusing headline.

    Sources for the ad and context:

    Bottom-line clarity for skimmers

    Headline: Samsung NZ ad. Cast: New Zealand Tim Cook. Motive: troll Apple as iPhone Duo debuts. Action item for readers: none, unless you were about to rewrite a procurement policy based on a meme. Then undo that commit.

    Bottom line

    Did Apple’s Tim Cook buy a Samsung Galaxy Fold? There is no credible evidence of that, and the viral claim collapses once you watch the ad: different Tim Cook, intentional confusion, timed to Apple’s foldable debut. Enjoy the joke. Then go read the hinge specs and the support matrix like an adult who has to keep phones working on Monday morning.

    Steve Miller — Mason, Ohio. Former programmer, sysadmin, and IT manager. Still resolves hostnames carefully.

  • Anthropic Says a Northern Yemen Cell Used Claude on Missile Software—Not a Finished Weapon

    Anthropic Says a Northern Yemen Cell Used Claude on Missile Software—Not a Finished Weapon

    The earlier stub treated “Houthis using Claude to design missiles” like a finished blockbuster plot. The primary document is colder, and more useful.

    Anthropic’s September 2026 threat-intelligence report describes a case (GTG-87001 in secondary coverage) in which a cell based in northern Yemen used Claude—especially Claude Code—to help develop guidance, navigation, and control software for three parallel projects: a guided rocket built around a commodity phone-class flight computer; a multi-stage ballistic missile with a stated range goal above 2,000 kilometers; and a multi-variant family (reported as “R2000”) that included a hypersonic-glide variant. Anthropic says the actors treated the model like a small engineering team—separate instances for coding, research, and review—while spreading intent across chats to dodge single-thread filters.

    What Anthropic did not claim

    Read the caveats before the memes:

    • Anthropic did not name the Houthis. Northern Yemen is largely Houthi-controlled, so inference is common in press coverage; that is geography plus politics, not a courtroom ID.
    • Anthropic says it has no evidence the actors fielded an operational weapon.
    • They did test-fire a guided rocket; the test appears to have failed. Within hours, the actors came back to Claude to debug why.
    • Safeguards blocked many requests, not all. Accounts were banned; findings were shared with authorities and industry partners.
    • Actors reportedly already had an offline simulation toolkit that did not depend on Claude—so ban-the-account is necessary and incomplete, the way locking one compromised laptop is incomplete if the malware was already copied.

    Primary and near-primary sources:

    The debugging lens (without cartoon missiles)

    What worries me is not sci-fi autopilot armies. It is labor substitution on the hard middle of engineering. Autopilot integration, control tuning, simulation loops, firmware build pipelines—those are exactly the tasks where a capable coding model compresses calendar time for people who already have hardware and intent. The report’s “lead engineer delegating to a small team” analogy is the part that should make export-control folks sit up.

    That is also why “we banned them after the schematics” is a real process failure mode, not just a punchline. Detection that fires after download is incident response, not prevention. Useful. Late.

    Policy without panic

    If you run AI platforms, cloud, or enterprise coding agents, the actionable checklist looks familiar:

    1. Domain-specific refusals for weapons GNC, energetics, and dual-use flight software—not only generic “harmful” buckets.
    2. Cross-session correlation. Split prompts are the adversary’s unit test of your monitoring.
    3. Uplift measurement. Anthropic talks about speed/scale/depth. Defenders need the same metrics, not vibes.
    4. Assume offline continuation. Once code and sims leave your API, your ban is a door lock after the USB stick walked out.

    Governments will argue about export controls and model weight thresholds. Fair. Operators should not wait for a perfect treaty to treat weapons-adjacent coding sessions like privileged production access—logged, reviewed, and killable.

    Where this sits among Anthropic’s other cases

    The September report is not only about Yemen. It catalogs cyber operations, influence factories, scams, and more—actors using Claude as orchestrator, not just chatbot. That broader pattern matters for defenders: the same agentic coding loops that help a startup ship faster help adversaries iterate malware and GNC software. If your security program still treats “AI risk” as deepfake HR videos only, you are a year behind the threat report you can download for free.

    I’m also uninterested in pretending bans are theater. They raise costs and interrupt live collaboration with the model. They do not confiscate offline toolkits. Layered controls—identity proofing, slow-ramp privileges for dual-use domains, human review queues for weapons-adjacent code—beat a binary free-for-all followed by a press release.

    Attribution hygiene

    Journalists will keep writing “Houthis” because northern Yemen’s map invites it. Analysts should keep writing “northern Yemen cell, attribution unconfirmed by Anthropic.” That gap is not pedantry. Bad attribution makes bad sanctions and bad detection signatures. Copy Anthropic’s nouns until better evidence lands.

    Bottom line

    A northern Yemen cell used a commercial AI coding stack to accelerate guided-weapons software work; a field test failed; Anthropic disrupted the accounts and published enough detail for the rest of the industry to stop pretending this class of misuse is theoretical. Calling it “Houthi Claude missiles online” oversells attribution and outcome. Calling it a nothingburger undersells how much engineering labor models can relocate.

    Steve Miller — Mason, Ohio. Former programmer, sysadmin, and IT manager. Prefers boring primary sources to cinematic stubs.